All Categories
Featured

Navigating the UK Enterprise Leadership Market in 2026
Table of Contents
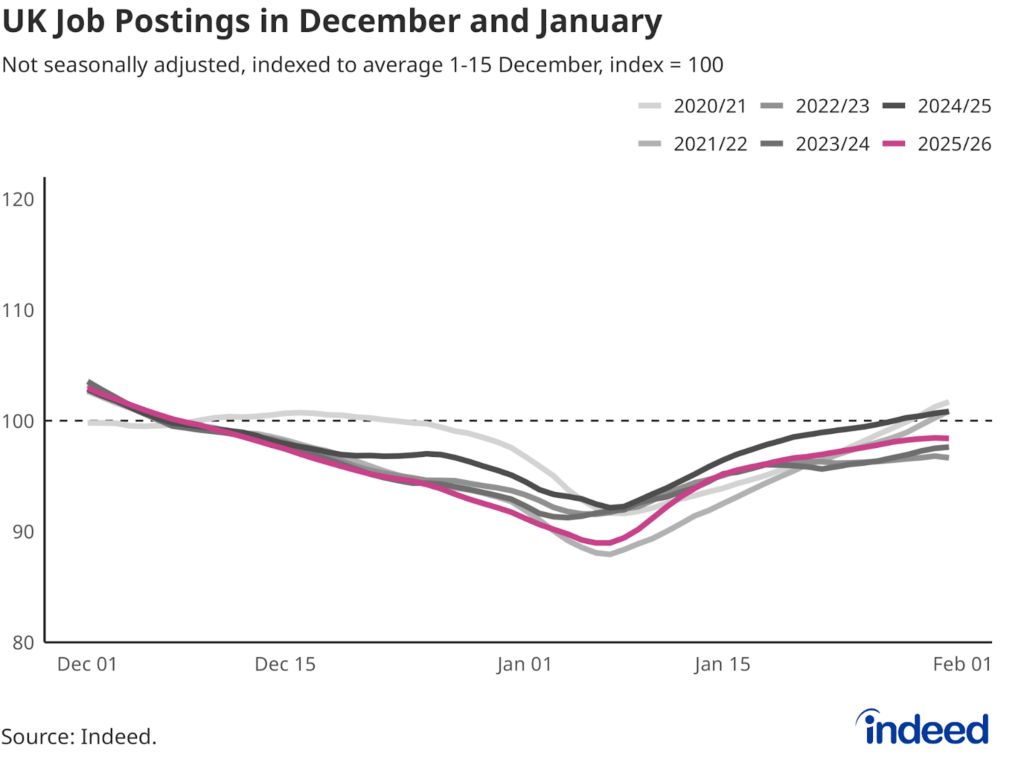
The vacancy-to-unemployment ratio supplies a useful lens here (figure B). While the labour market has cooled considerably from the exceptional tightness of 2021-22, jobs have actually more just recently stabilised even as unemployment has continued to edge up. This pattern recommends that the modification in the labour market is increasingly taking place through slower hiring and weaker task matching.
While our main forecast does not presume such a shift, this is an important danger that we are keeping an eye on carefully. Proof from organization surveys recommends AI is currently being used generally to augment particular tasks especially in administrative, analytical and customer-facing functions instead of to drive large-scale workforce reductions. Documented efficiency gains have actually so far been concentrated in narrow functions, with restricted instant effect on overall work.
For the Monetary Policy Committee, the crucial judgement is how rapidly rising joblessness equates into lower wage growth and services inflation. While we anticipate Bank Rate to fall to 3.25 per cent by year-end, persistent wage pressures provide a danger to this view. For the public financial resources, slower employment growth and weaker earnings characteristics would minimize income tax and National Insurance coverage invoices.
The UK economy will grow more gradually next year than any other significant sophisticated nation as taxes and high interest rates take their toll, according to the latest projections from the OECD. In a bleak outlook, the Organisation for Economic Co-operation and Advancement downgraded its forecast for UK development from 0.7 per cent to 0.4 per cent, the least expensive in the G7 apart from Germany.
In 2025, it predicts that the UK will grow by 1 percent the weakest performance in the G7. By comparison, the US economy is anticipated to power ahead this year with 2.6 percent development, followed by Canada at 1 percent, and Italy and France at 0.7 per cent.
Strategic Management Insights for Agile Corporate Excellence
German financial development is forecast to increase from 0.2 percent this year to 1.1 per cent next year, which will see it leapfrog Britain. The OECD outlook is more downhearted than that provided by the International Monetary Fund (IMF) previously this year, which forecast UK growth of 1.5 percent.
Interest rates required to remain high in order to deal with sticky inflation, it stated. "The fiscal and monetary policy mix is sufficiently limiting and ought to remain so until inflation returns durably to target (2%)," the OECD's UK financial outlook for 2024 discovered.
The OECD anticipates eurozone inflation currently 2.4 percent will be considerably lower than UK inflation currently 3.2 per cent over the same period. The think tank said "fiscal prudence" is needed until the Bank of England's inflation target of 2 per cent is met, which government spending need to be directed towards "supply-enhancing investment" such as the NHS.
Investment Banking Trends Shaping UK Mid-Market Strategy
The unemployment rate increased to 4.2 percent for the most recent three-month duration to February. The OECD anticipates this will continue to increase, reaching as high as 4.7 percent in 2025 "as the labour market cools". Chancellor Jeremy Hunt said the OECD forecast was unsurprising provided "our concern for the last year has actually been to tackle inflation with higher rate of interest.
Get newest updates and insights provided to your inbox.
[LONDON] The International Monetary Fund raised its growth projection for Britain's economy this year on Monday (May 18) but warned that more "domestic unpredictability", at a time when political instability is engulfing the federal government, could strike spending and financial investment. In an upgrade that financing minister Rachel Reeves hailed as a sign of progress by embattled Prime Minister Keir Starmer's government, the IMF stated Britain's economy would grow by 1.0 per cent this year.
It would still represent a downturn for Britain from 2025." While the UK economy has stayed resilient recently, the war in the Middle East is moistening near-term prospects," the IMF said in its annual evaluation of Britain's economy. The new, greater forecast for 2026 was due to pre-war financial momentum which was shown in current stronger-than-expected growth and modifications to previous information, the Fund said.
Future Business Finance Projections for UK Mid-Market Sectors
However, provided the uncertainty about the Iran dispute, the BOE might have to cut or raise rates and should "be prepared to react powerfully" if second-round effects such as worker demands for greater pay or companies raising their selling costs showed more powerful than anticipated. Over the past two weeks, British politics has been rocked by speculation about Starmer's future, driving benchmark 10-year borrowing costs to their highest because 2008 on Friday on the prospect of weaker fiscal discipline.

Latest Posts

How Global Mid-Market Strategy Evolves for 2026
Why Global Trade Dynamics Matter for British Firms

Modernising Mid-Market Capital Markets Via Digital Reform